

China has a big ‘‘secret’’ weapon in this AI race. It’s not cheap labor and it’s not a fast-growing economy. It’s a lot of very cheap energy, ready to be used.
China spent the last decades building an energy infrastructure they didn’t know they needed. They invested heavily in energy infrastructure to meet economic demand, mostly for housing and industry.
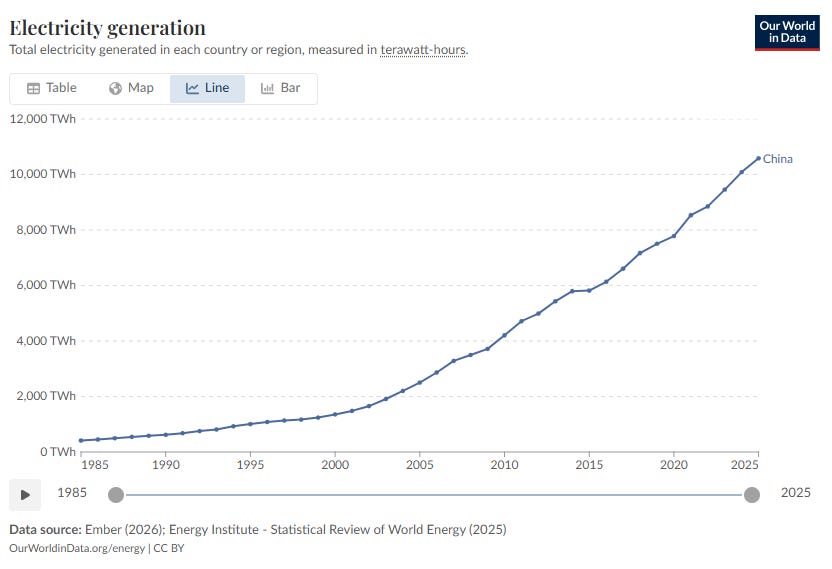
That demand?
It did not arrive. At least not in full.
Lucky for them, because that excess capacity is now more welcome than ever and I believe it’s actually their most valuable asset in this AI buildout.
Getting capacity online
While the US struggles to get capacity online, and let’s not even get started on Europe, China has been building the foundation to meet and deal with future energy problems, and the funny thing is they did so mostly by accident.
Energy demand problems and capacity restraints are not some futuristic issue to tackle. The struggle for energy capacity is happening right now, right under our noses.
Microsoft’s CEO Satya Nadella said:
Microsoft doesn’t have enough electricity to install all the AI GPUs in its inventory - ‘you may actually have a bunch of chips sitting in inventory that I can’t plug in’
And they are not the only ones with this problem. Many large companies have made similar statements. Tesla, Google and Amazon are all dealing with this issue as well.
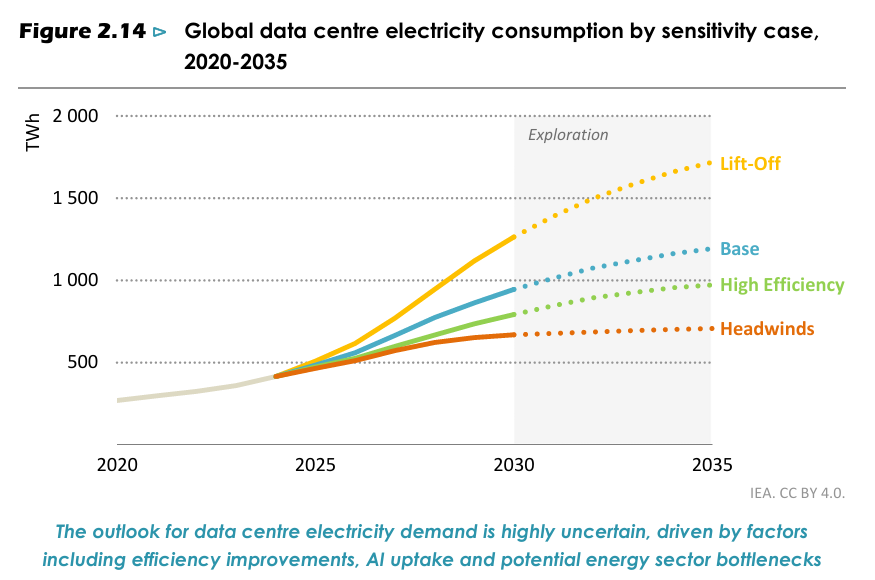
But it seems the problem might get even worse from here. According to the IEA , Electricity consumption for datacenters is expected to more than double from here.
In a bull-scenario it could even more than triple by 2030.
Without capacity, these plans are just thoughts.
Most national energy infrastructure systems in the world are far from ready to meet that enormous demand. Demand is rising fast and it’s not just because of datacenters.
You also have climate goals that require the heavy industry to go green. They can only do so with electricity for now because fuck hydrogen.
Improving and expanding the grid is not as easy as China made it seem.
The IEA projects US data center electricity demand to grow by roughly 240 TWh between 2024 and 2030 which is a 130% jump.
China is expected to add about 175 TWh over that same period.
The big difference, China is ready to face demand increases. The US is still very busy building the infrastructure. Europe doesn’t really know what it’s doing to be honest. They are standing still
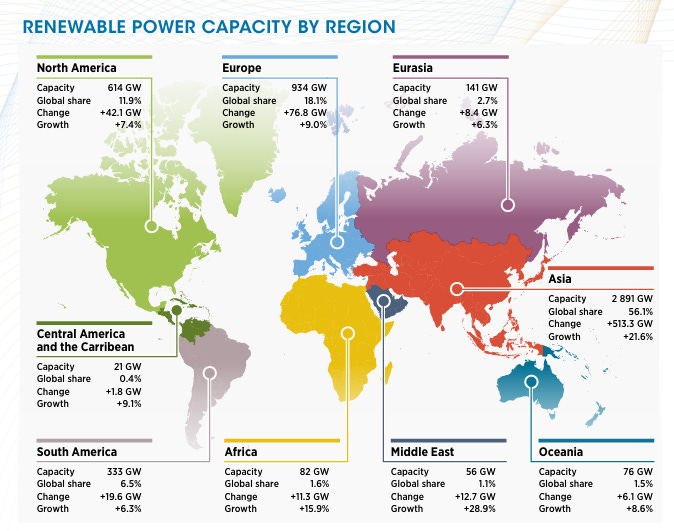
Asia already holds 56.1% of total power capacity and they are still rapidly expanding. Not only do they have the biggest share, they are also growing 2x or 3x the speed of Europe and the US.
In 2025 alone, China increased its wind and solar power capacity by more than 430 gigawatts, accounting for more than half of the additional capacity in the renewables added globally that year.
The generation and connection bottlenecks
So what is holding the US and Europe back?
It’s actually two things: the first one is the most obvious, generation. The second one is a bit more complex and less obvious, connection.
The easiest question to ask is: is there enough generation capacity to meet demand?
For now the answer is YES. But, it’s getting more and more tight.
Goldman Sachs found that American peak summer spare capacity has fallen from 26% five years ago to 19% today. If expansion continues at the current pace and it drops under 15% by 2030, the situation gets a lot more critical .
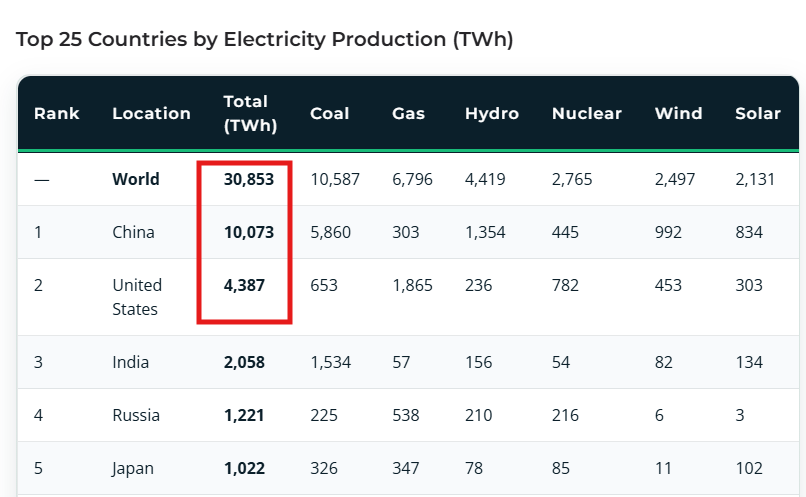
China faces a similar curve. About 175 TWh of new data center demand by 2030. The big difference is that China generates over 10,000 TWh a year today, more than double the amount of the US. They have a lot more wiggle room.
China is ready, the US is getting there. Europe is going backwards.
The second and in my opinion even more critical questions to ask; Can this capacity can actually be used? You can build all the power plants in the world, but if you don’t connect them to the grid, they’re useless.
And I can tell you for a fact, connection is the issue. In the US, over 2,060 GW of new power projects were sitting in the connection queue at the end of 2025. That's twice as much as the entire American grid can currently produce.
Wait time? 5-7 years, minimum. The picture below shows the lead times back in 2023, and it certainly hasn’t improved since then.
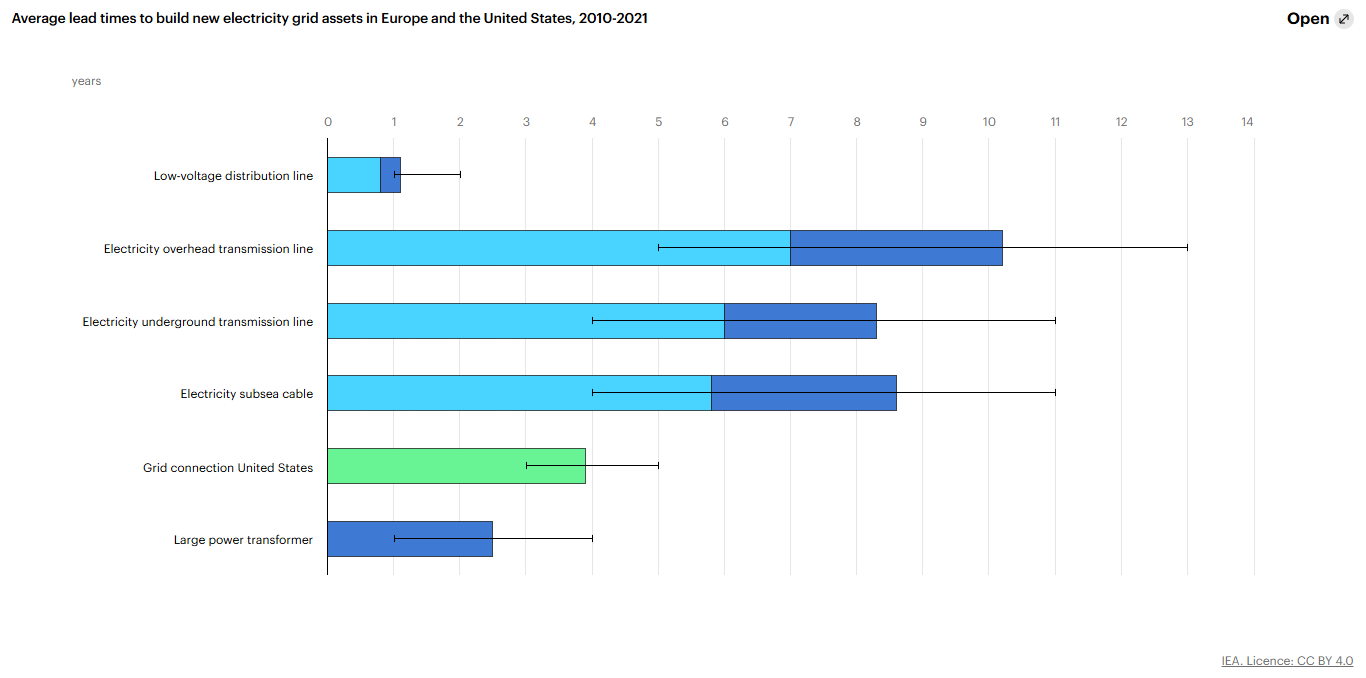
Most projects and business plans cannot wait that long, so a lot of them give up before they have the chance to go online at all.
Europe? It’s even worse.
Europe used to be the big datacenter hub, holding about 1/4th of total datacenter capacity in 2015. Now that’s below 15%.
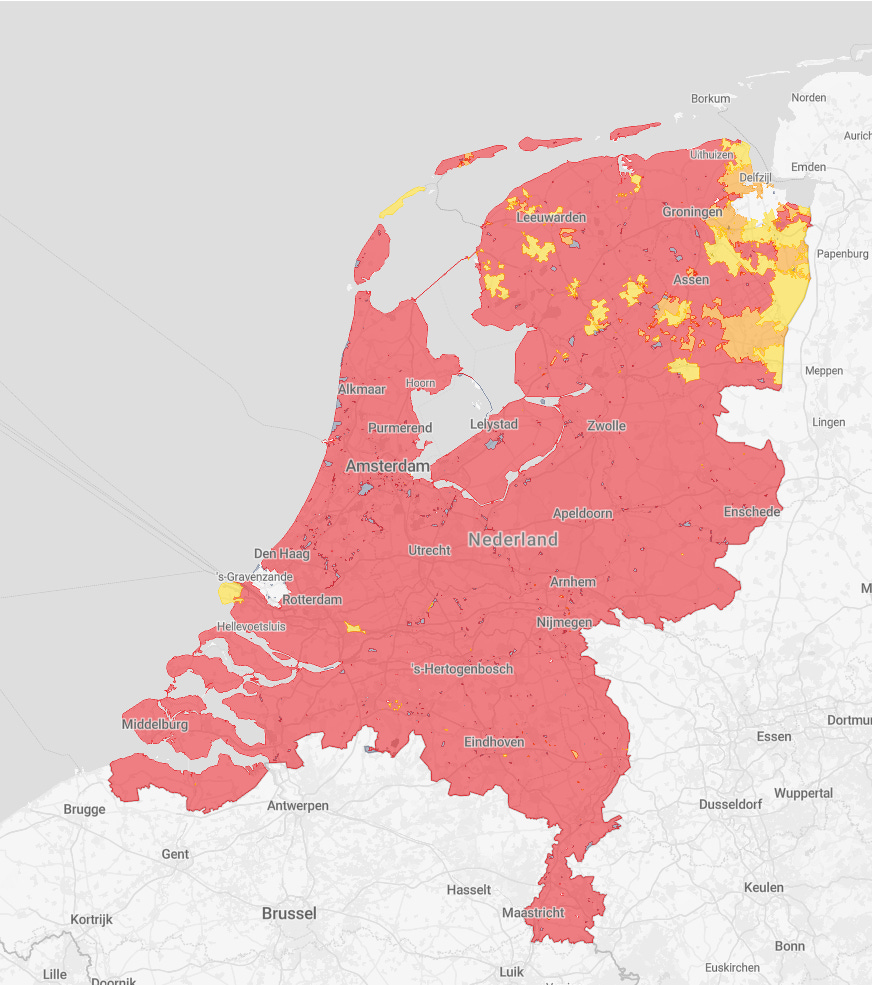
Same issue here, but even longer waiting times. In a lot of European countries, like the Netherlands and Denmark, the grid operator simply stopped accepting new connections in some regions. There’s simply no space on the grid.
This is the congestions map in the Netherlands. Red is full.
Europe has an extra problem on top of it, the grid is old. About 30% of distribution networks are over 40 years old, and that hits 50% by 2030. The grid is more than ready for maintenance, and it won’t be cheap.
Also keep in mind, electricity in Europe is very expensive. Often 3x or 4x of what it costs in China or the US.
This cocktail makes Europe less and less attractive, for datacenters but also for industrial expansion or greening ambitions.
So what now?
Let’s draw some conclusions:
The common theme: energy is the bottleneck.
China is ready, they have the power and the connections. The thing they don’t have: the ability to turn this into compute efficiently and in large scale like the US, at least not for now.
The US is doing fine. They have the chips, the capital and the compute. But they are on the verge of having major grid connection issues.
Europe has nothing. They have an aging grid, high electricity prices and major capacity issues and no concrete plans to speed things up for improvement.
If you believe this AI buildout continues, and every capex number says it does, then you should also believe this major energy-hurdle can become a lot bigger in the future.
My conclusion is simple.
If the US and Europe want to catch up, they will have to invest. A lot.
That creates opportunity. And I think there are some great companies to look into that help solve the problems we talked about. Unfortunately quite a few of them run up, but I believe we still have a long way to go.
If connection is really the issue, money will flow to companies that fix the issue.
Grid equipment is the obvious one. Think along the lines of: transformers, switchgear. Here you have companies like Hitachi, Siemens Energy, Schneider, Eaton, GE Vernova. Lead times on large transformers are already 3-4 years. These companies sit in the chokepoint and will benefit from it.
Next up, the electrical contractors who do the actual work. Here we have names like Quanta Services, MYR Group, IES Holdings. Someone has to build the interconnection, and there aren’t enough of them.
Then there’s the sneaky one: utilities that are already connected. Vistra, Constellation, AEP, Dominion. They are not valuable because they generate power. They are valuable because they are already online. They have capacity.
Another solution is on-site generation. Some names to check out are Bloom Energy for on-site generation + Caterpillar and Cummins for the generators.
I hope you enjoyed, because that’s it for now!
Until the next one, Cheers,
TacticzHazel

Disclaimer
The content I share is for educational and informational purposes only. It should not be considered financial, investment, or trading advice. All opinions expressed are personal views and are not guarantees of future performance. Investing involves risk, including the potential loss of capital, and past results do not indicate future returns.
Before making any investment decisions, you should conduct your own research or seek guidance from a licensed financial advisor. I am not responsible for any financial outcomes resulting from actions taken based on the information provided.
By engaging with this content, you acknowledge and agree that you are solely responsible for your own investment choices.
interesting read, enjoyed it!
Great article. Interesting that you include Bloom Energy, have you read the recent Hunterbrook investigation? (https://hntrbrk.com/investigations/bloom)